

CPI releases are among the most heavily traded macro events in the market.
The assumption is that a meaningful inflation surprise should create a clean directional move.
High-frequency data shows something much messier.
Across 30 major CPI releases from January 2024 through July 2026, the first reaction behaved much more like noise than a reliable signal.
The first five minutes were close to random
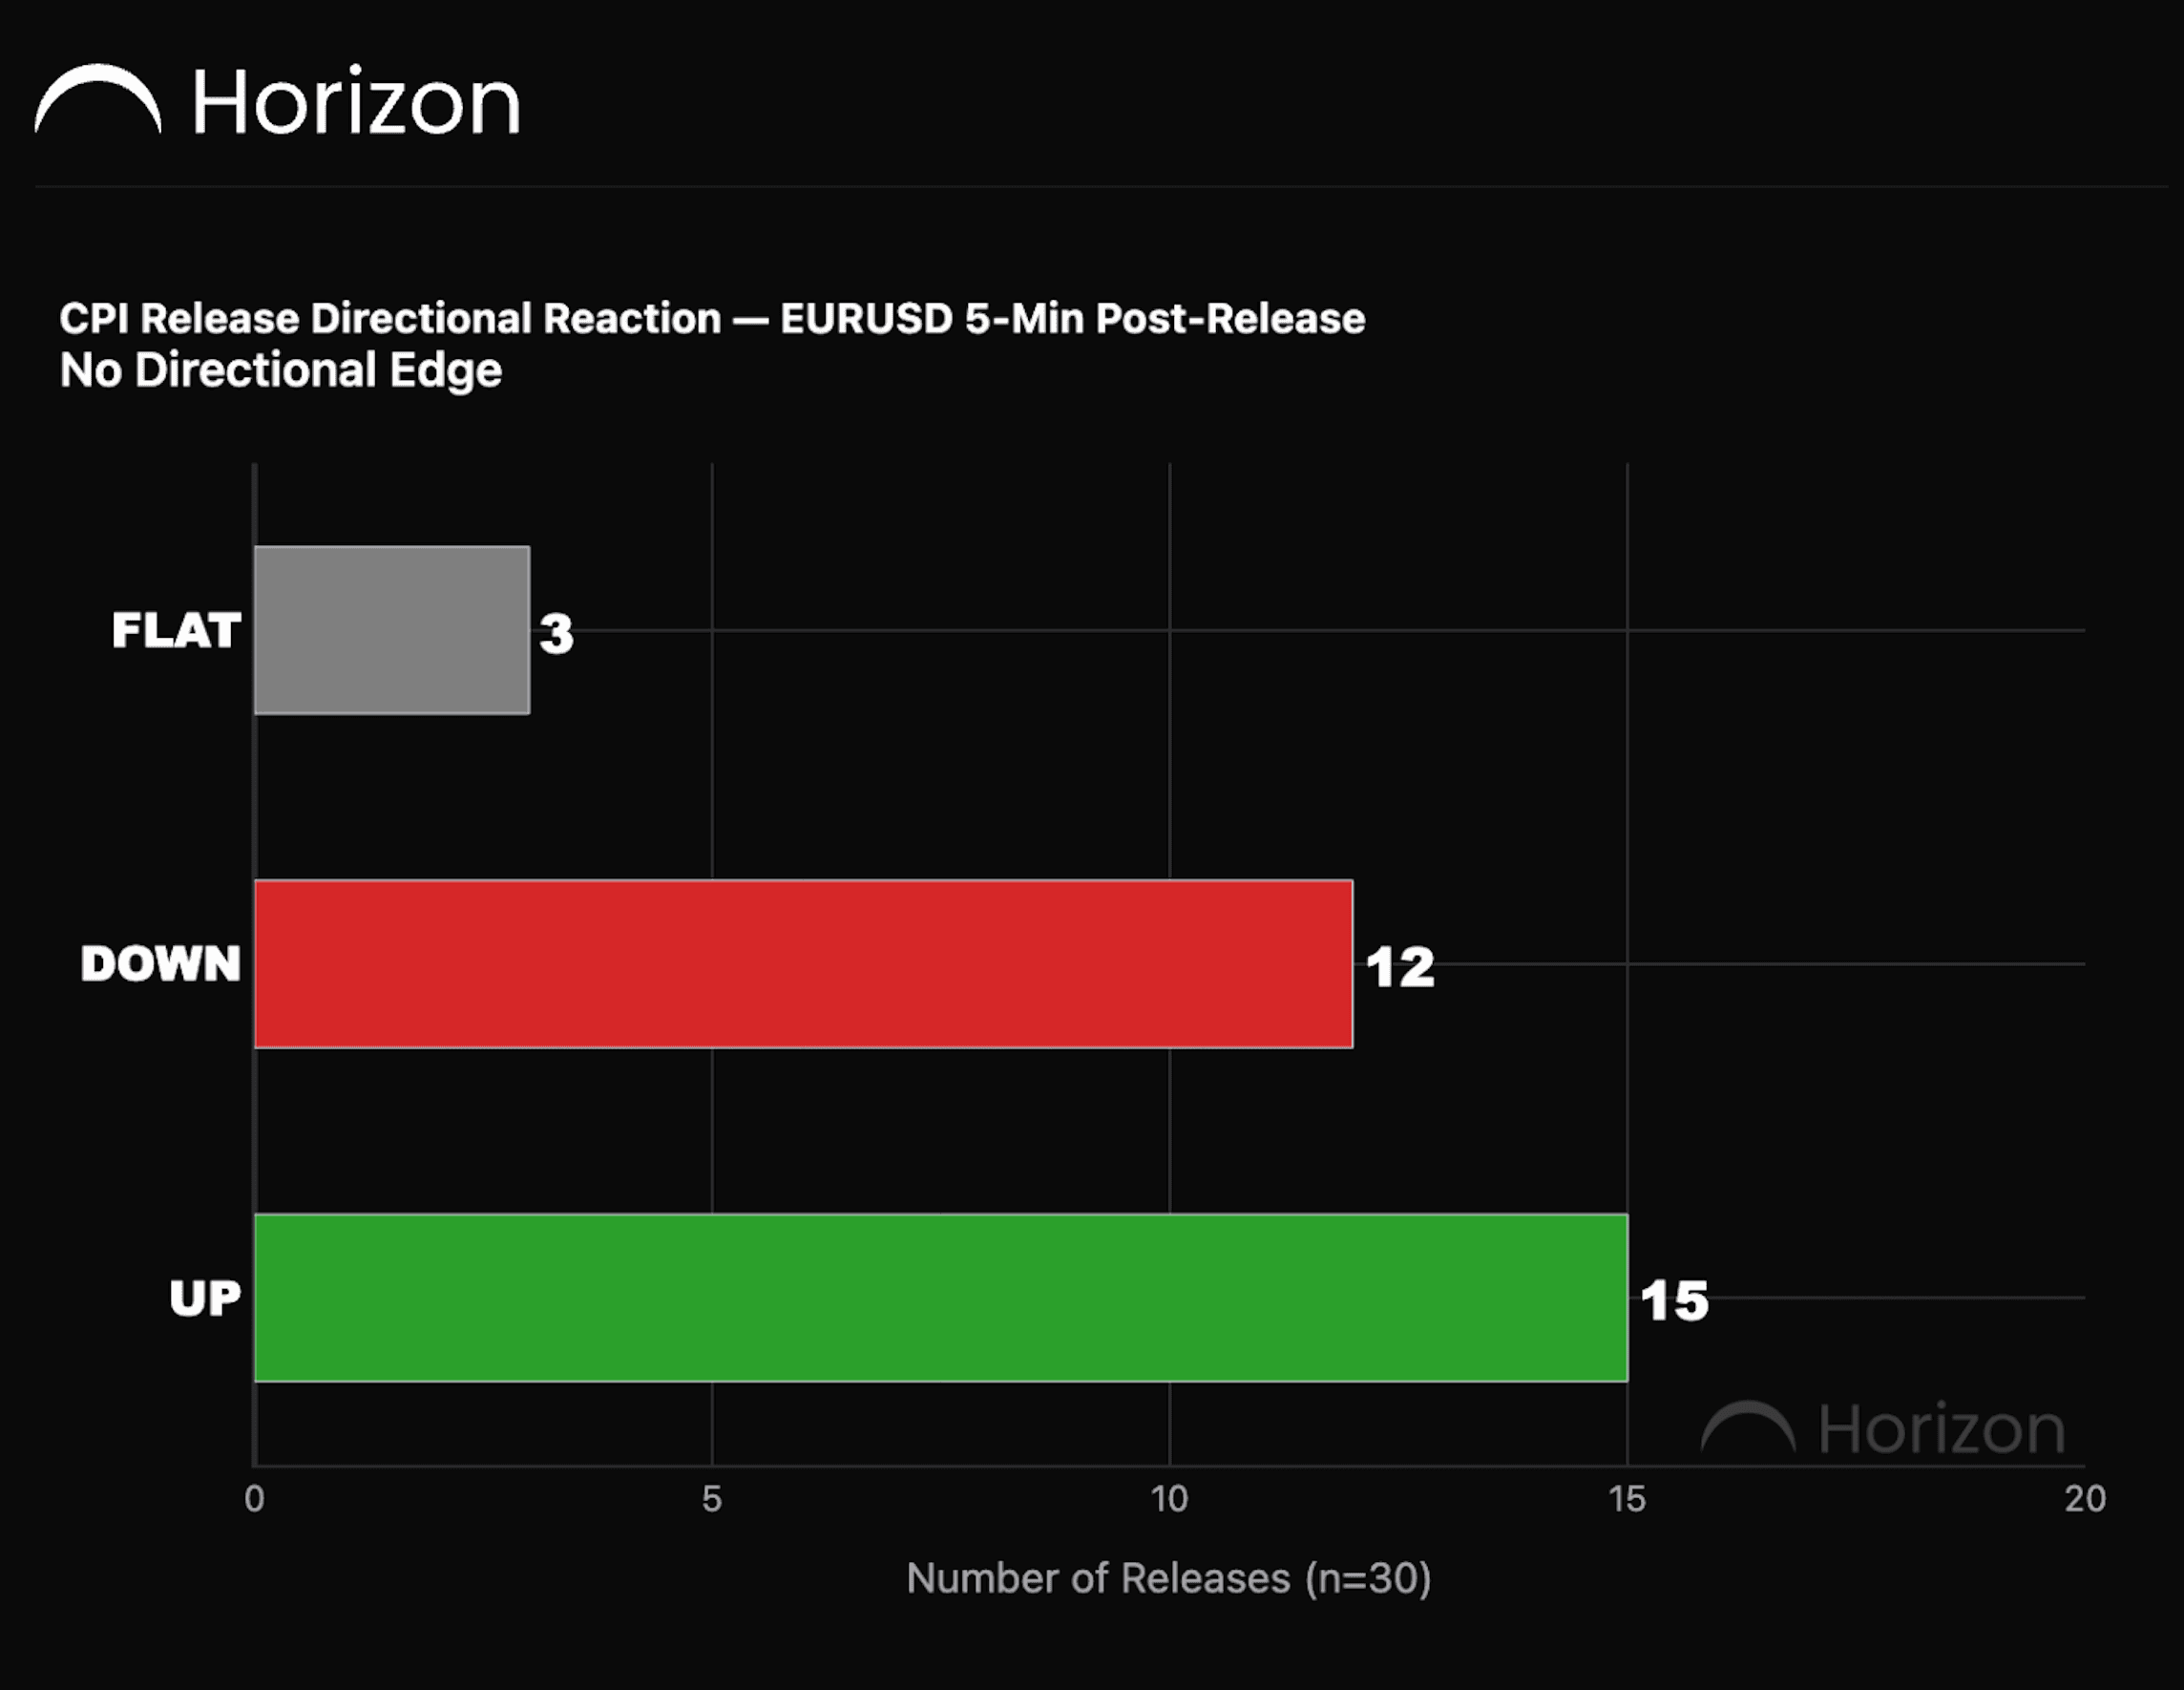
Using EURUSD as a high-frequency example, the initial five-minute reactions were:
- 15 up moves
- 12 down moves
- 3 flat moves
A binomial test produced a p-value of 0.7011.
That means there was no statistically meaningful directional bias in the first move.
Trying to predict whether the initial candle would be green or red offered no obvious edge.
The first move often reversed anyway
Even when the initial direction was correct, the move frequently failed to hold.
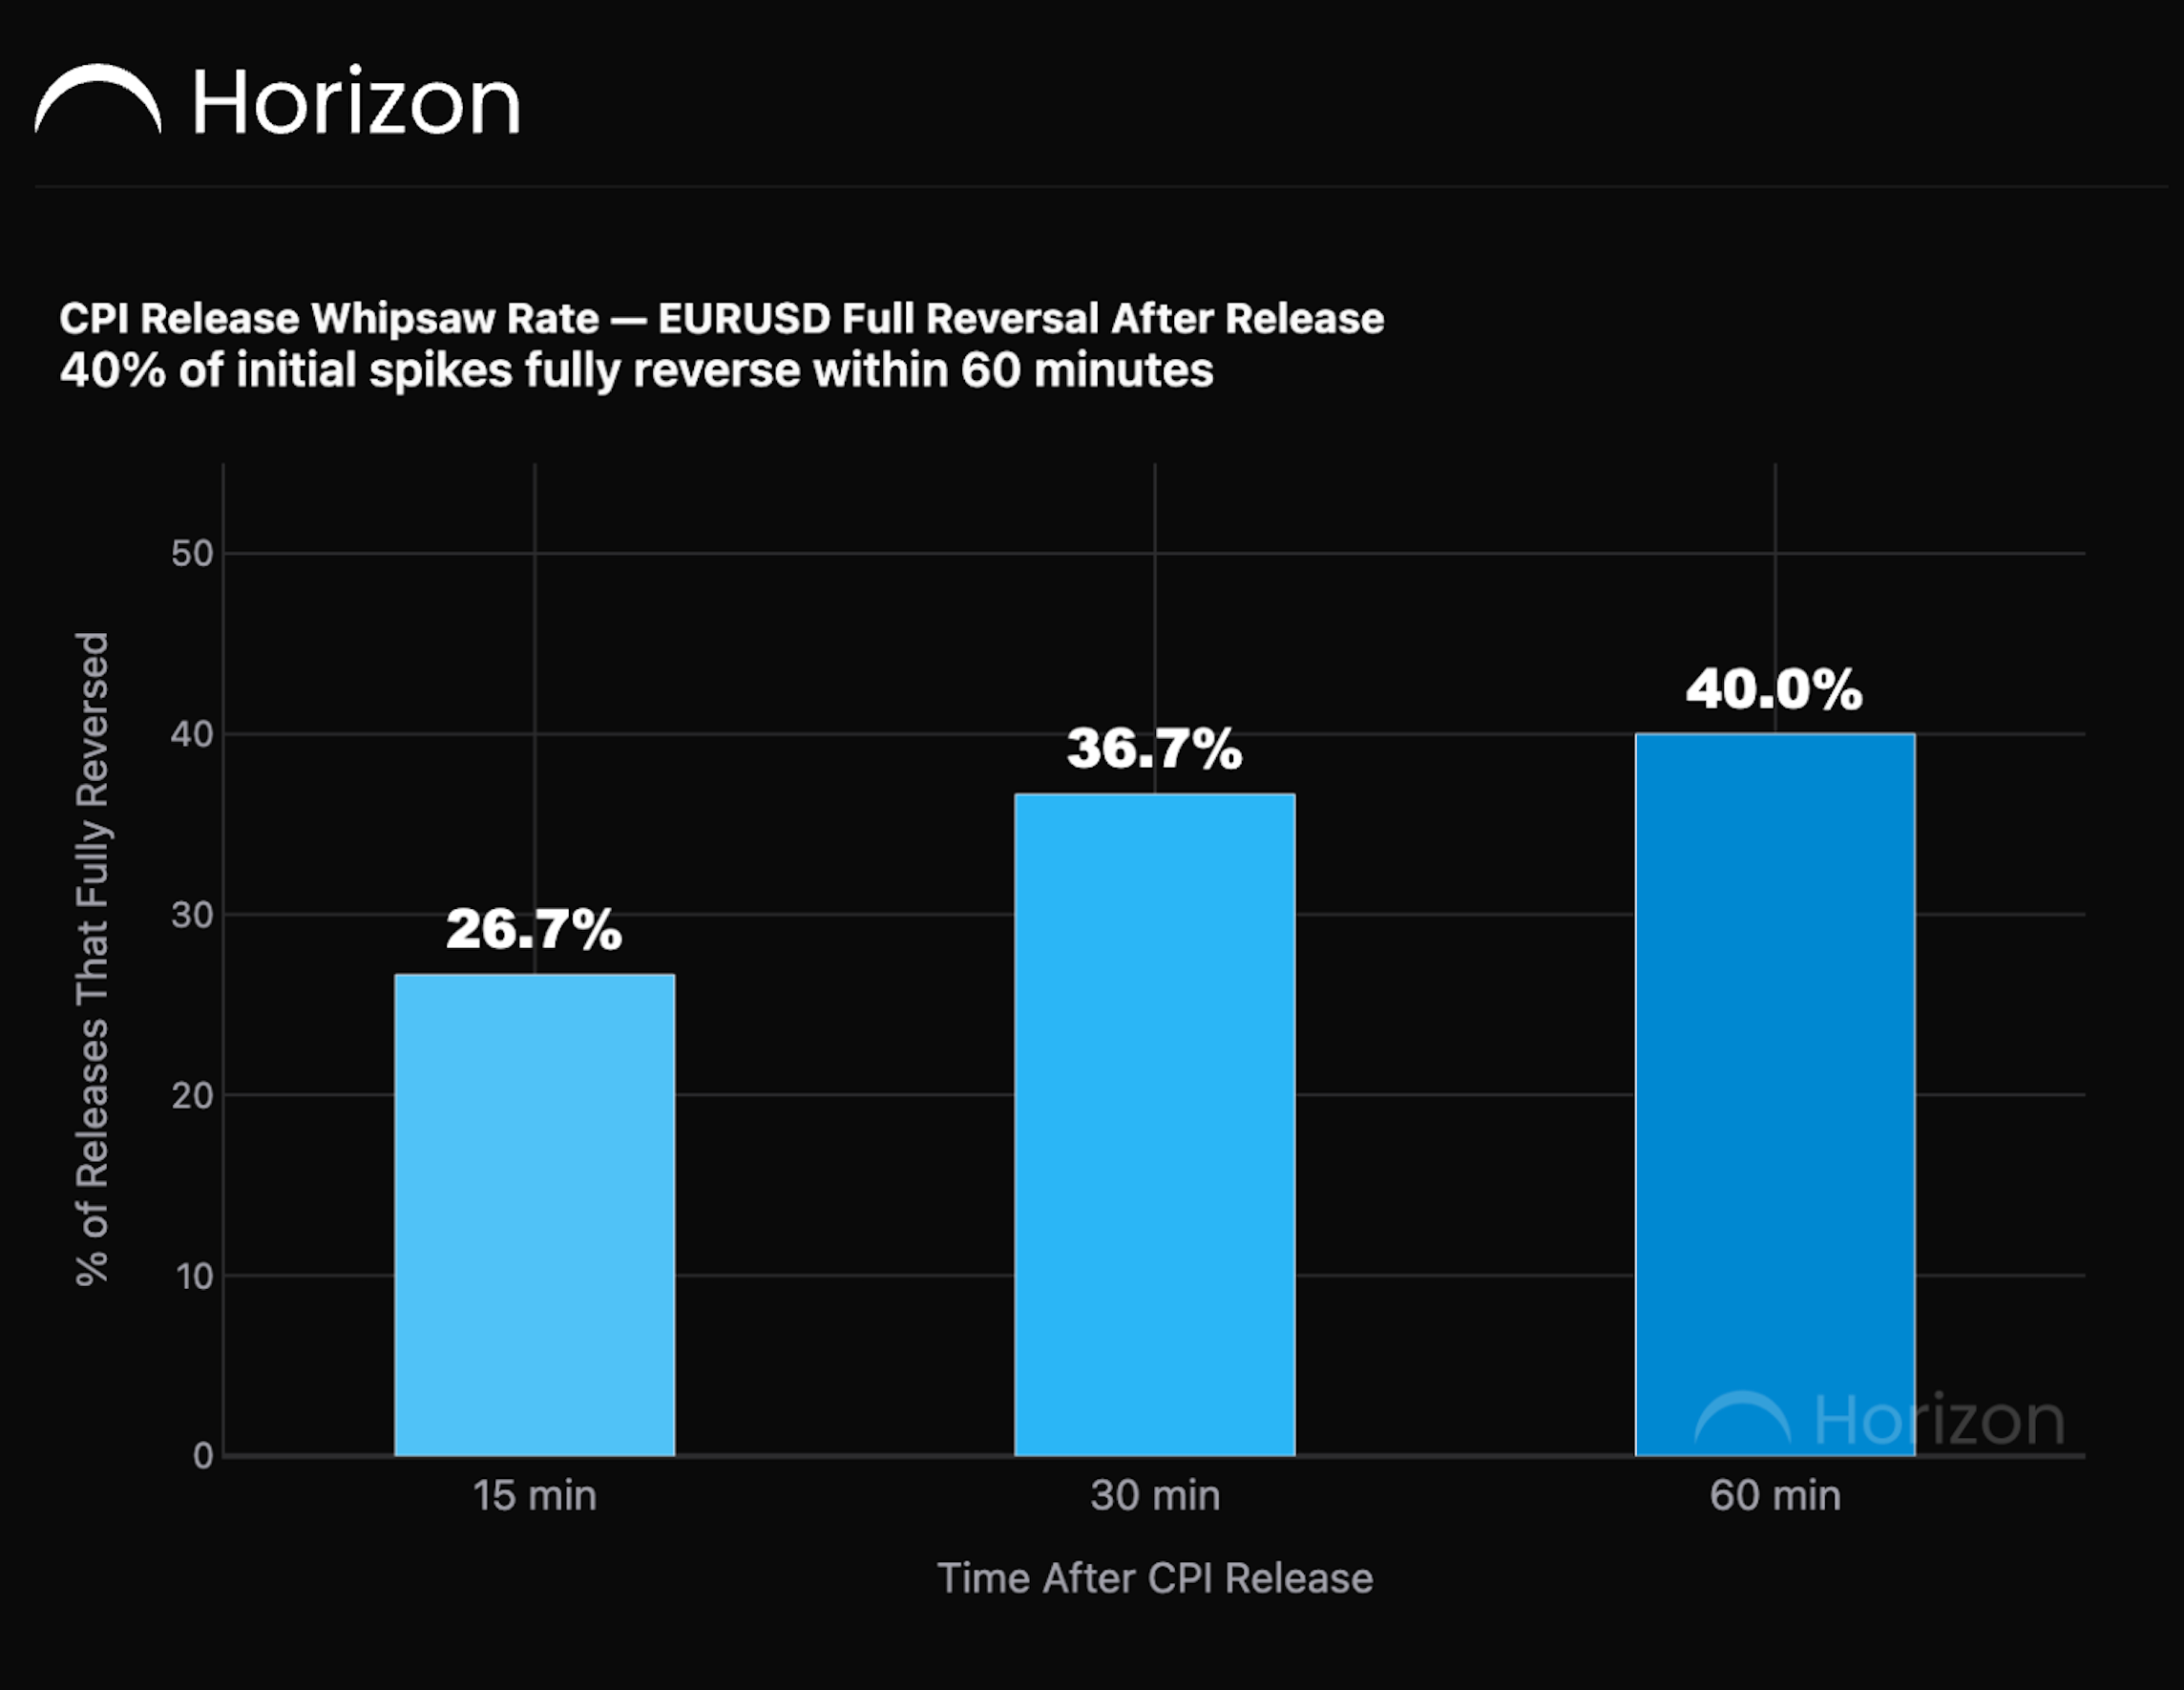
The full-reversal rates were:
- 15 minutes: 26.7%
- 30 minutes: 36.7%
- 60 minutes: 40.0%
By one hour after the release, four in ten initial CPI moves had completely reversed back through their starting point.
That is a difficult environment for simple breakout logic.
SPY showed the same problem in a different way
For U.S. equities, CPI often creates a meaningful pre-market gap.
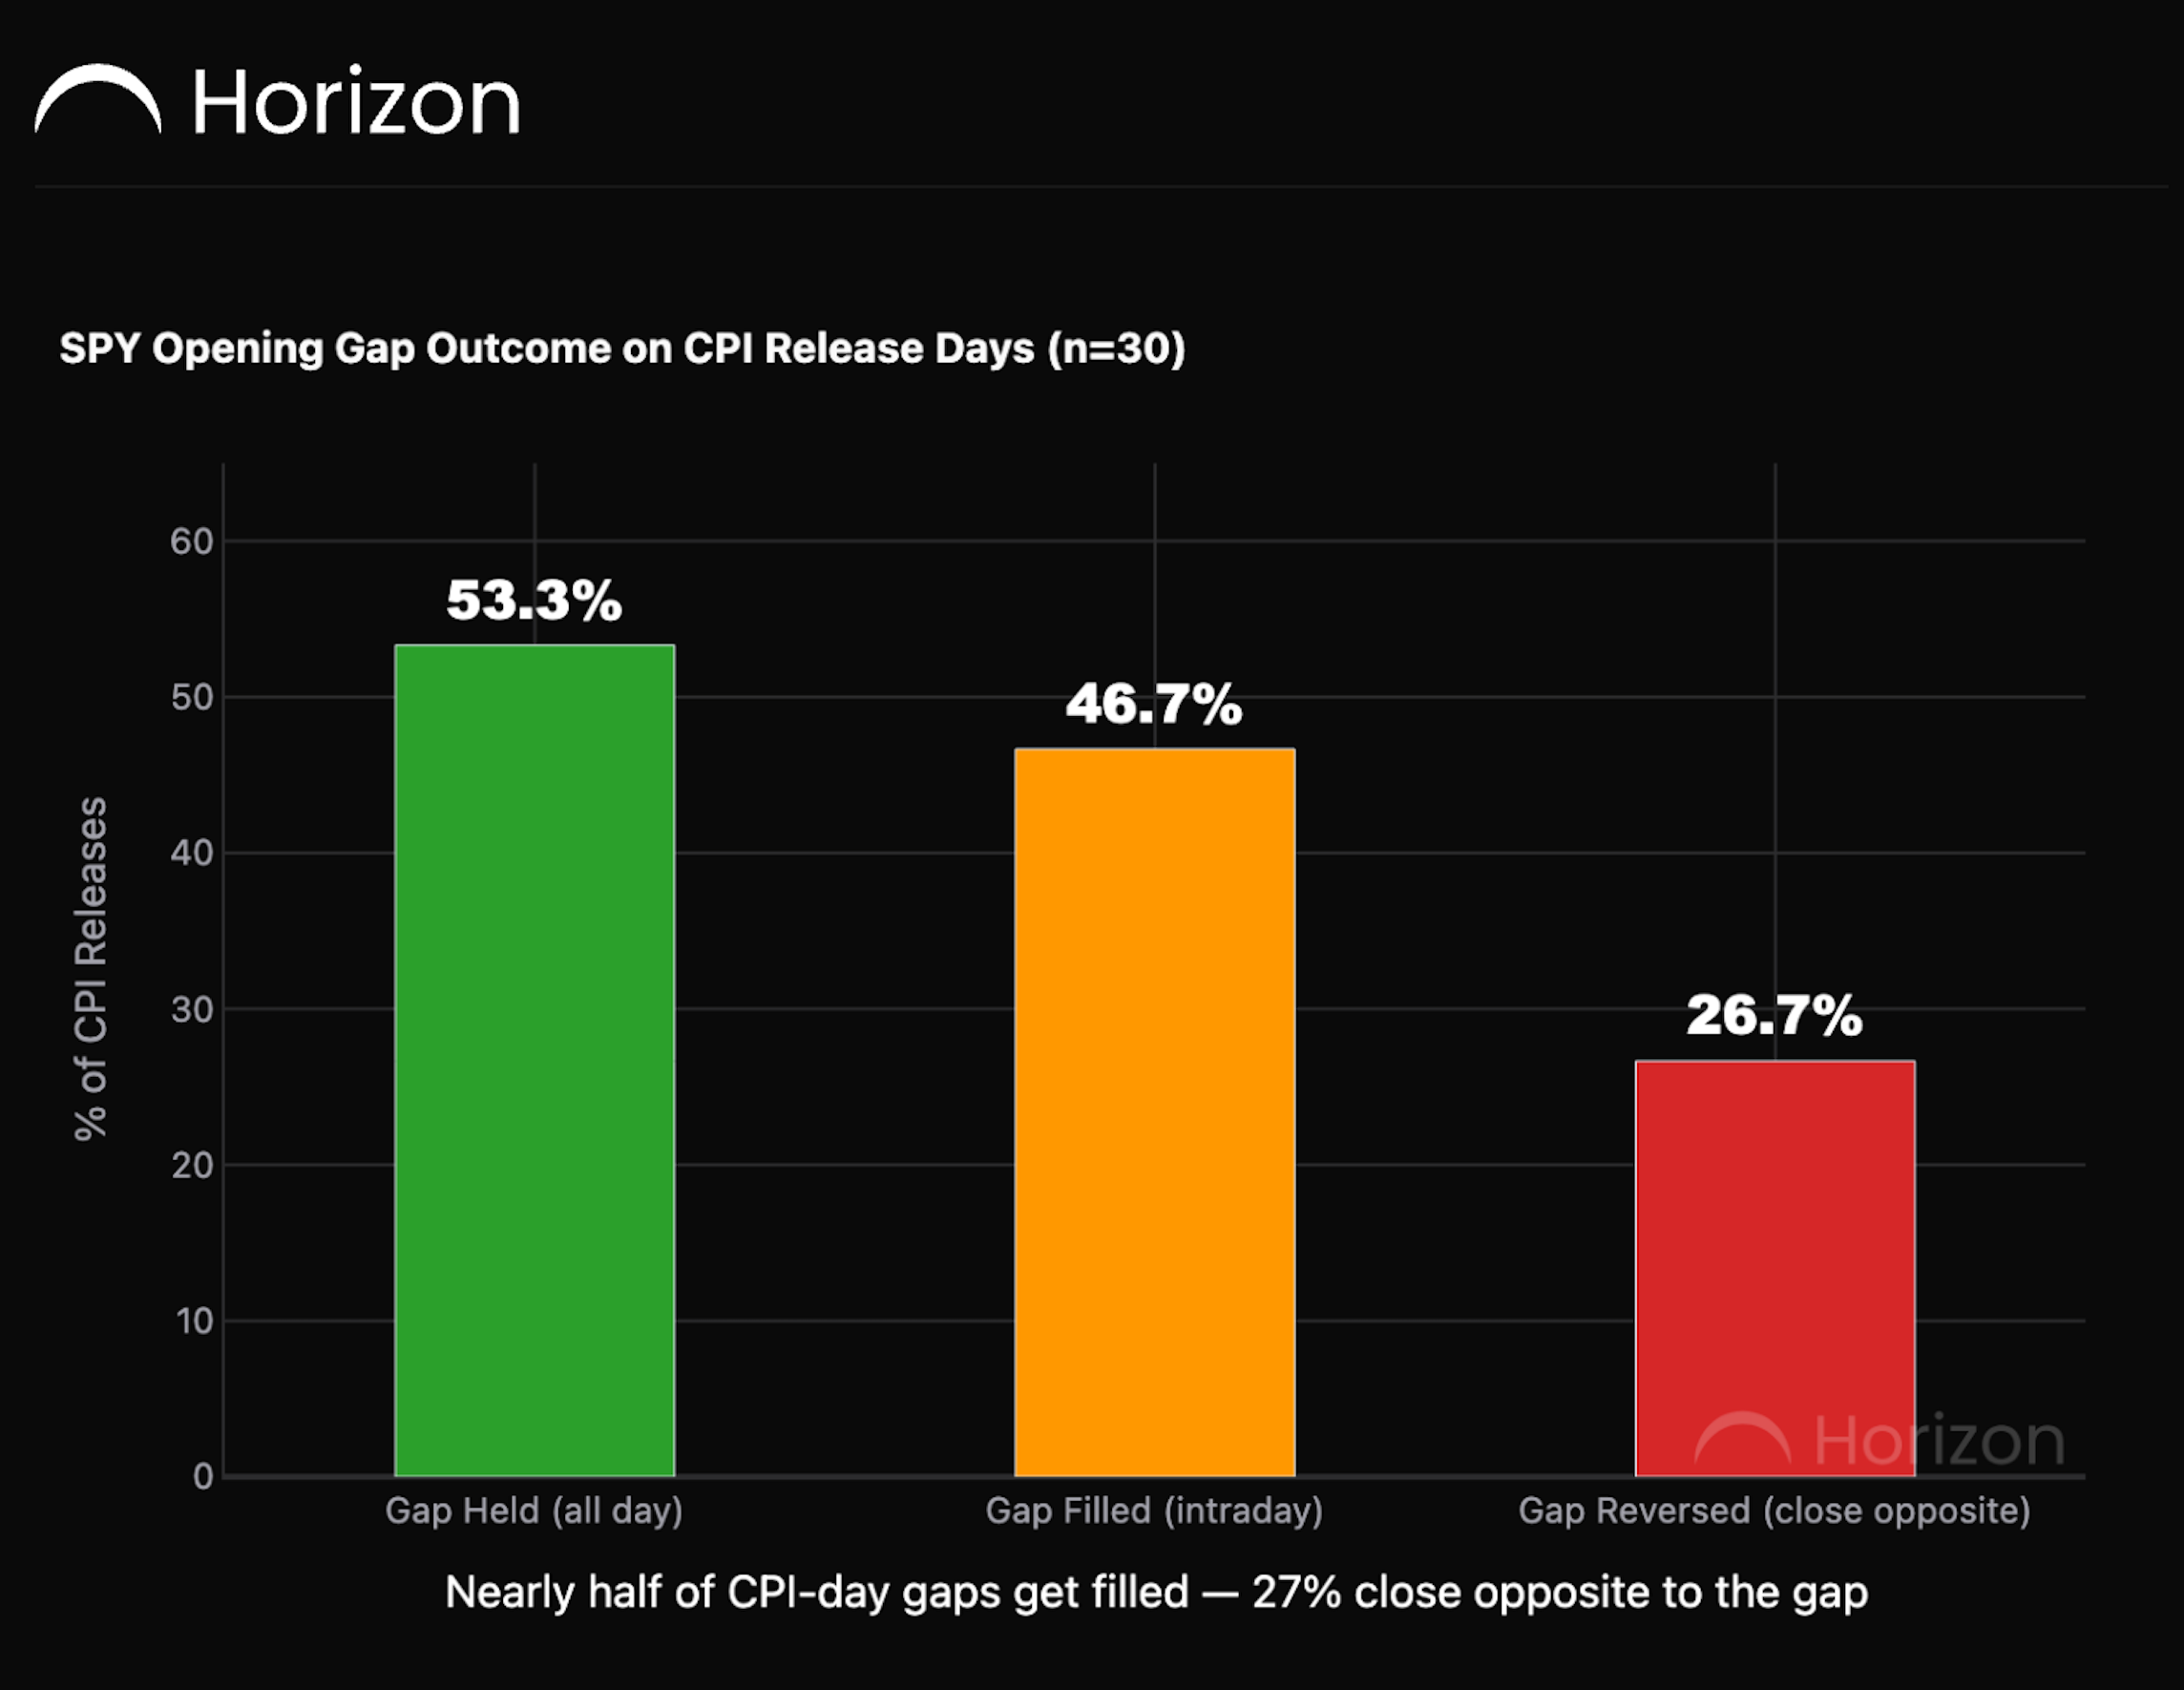
Across the same sample:
- 53.3% of gaps held through the day
- 46.7% were filled intraday
- 26.7% fully reversed to close on the opposite side of the opening direction
Again, the market showed some persistence, but nowhere near enough to treat the first move as clean information.
Why CPI is so difficult to trade
The headline number is only one input.
Core inflation, revisions, positioning, rates, the dollar and what the market already expected all matter at the same time.
Execution conditions are also worse immediately after the release.
Spreads widen, liquidity shifts and prices move before discretionary traders can process the details.
That makes a theoretically good macro call difficult to monetise.
The takeaway
The first CPI move has historically offered very little directional edge.
The immediate reaction was close to random, and 40% of initial moves fully reversed within an hour.
The lesson is not that CPI does not matter.
It clearly does.
The lesson is that market relevance and tradability are not the same thing.
Share this post:




