

Jackson Hole gets enormous attention every year.
Markets dissect every sentence from the Federal Reserve Chair for clues about rates, inflation and the policy outlook.
That makes the event feel like it should produce a clear directional edge in technology stocks.
Historically, it has not.
Twenty-two Fed Chair speeches
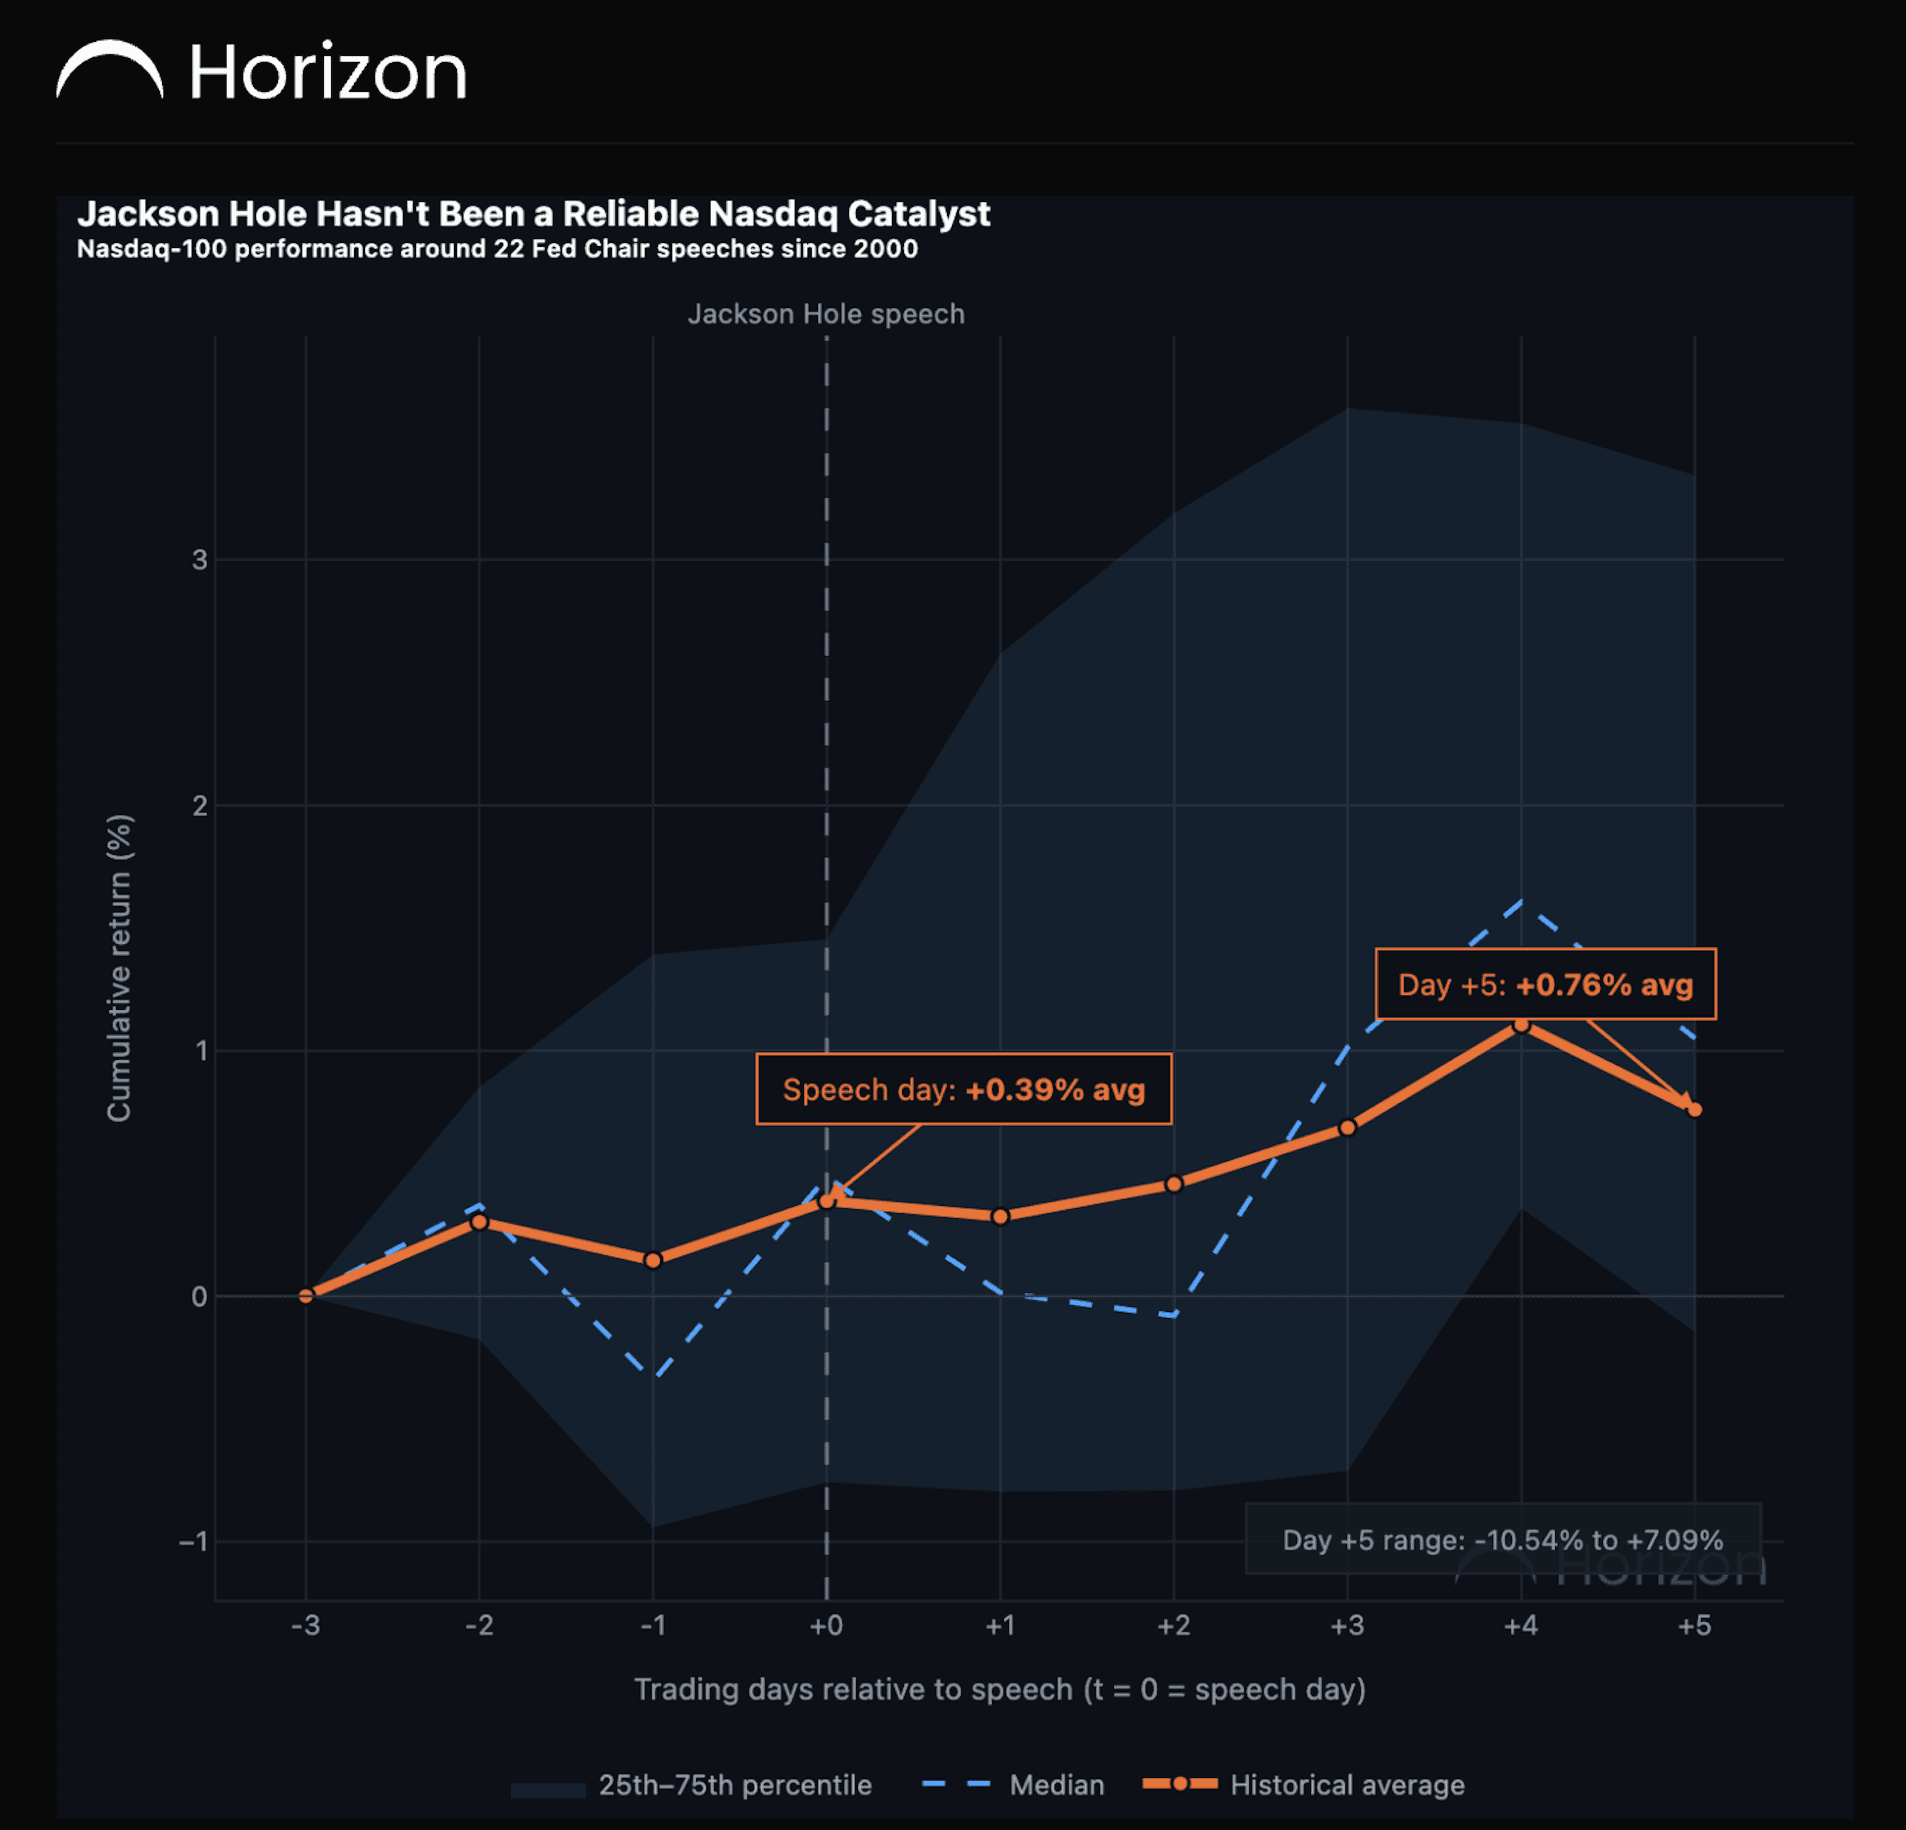
We looked at 22 Federal Reserve Chair speeches at Jackson Hole since 2000.
The Nasdaq-100 averaged just +0.39% by speech day.
By Day +5, the average return was +0.76%.
The median Day +5 return was +1.05%.
Those numbers are mildly positive.
They are nowhere near strong enough to call Jackson Hole a reliable bullish catalyst.
The dispersion is the real story
Five days after the speech, historical outcomes ranged from -10.54% to +7.09%.
That spread is enormous.
The standard deviation of post-speech returns rose to 4.16% by Day +3, roughly double its level on speech day.
In other words, the event produced much more variability than directional consistency.
Why the speech itself is not the signal
Jackson Hole is not a standardized event.
The Fed Chair does not deliver the same message every year.
Sometimes the speech confirms what markets already expect.
Sometimes it changes the expected path of rates.
Sometimes the macro environment overwhelms anything said at the conference.
That makes the label "Jackson Hole" much less important than the policy information delivered inside it.
What traders should actually care about
The useful question is not whether Jackson Hole has historically been bullish or bearish.
It has not been reliably either.
The better question is whether the speech changes the market's expectations for future policy.
That is what can move yields, equities and currencies.
The event creates the opportunity for repricing.
The message determines the direction.
The takeaway
There is no strong historical case for being bullish or bearish the Nasdaq-100 simply because Jackson Hole is approaching.
Across 22 speeches since 2000, the average five-day return was only +0.76%.
What the event has produced much more consistently is wider dispersion after the Chair speaks.
Jackson Hole matters.
The name of the event is not the signal.
The change in policy expectations is.
Share this post:




